- Remittance services turn a simple sari‑sari store into a neighborhood financial hub.
- With BSP pushing for a cash‑lite economy, small stores are now the “last‑mile” access point for money transfers.
- Becoming a remittance agent is legal, low‑cost, and highly profitable when done properly.
- This guide explains the requirements, process, earnings, and compliance rules.
In many barangays, the sari‑sari store is more than a place to buy soft drinks or noodles, it’s the community’s most accessible financial service point. As more Filipinos rely on digital wallets and domestic remittances, offering money transfer services can significantly increase your store’s income and foot traffic.
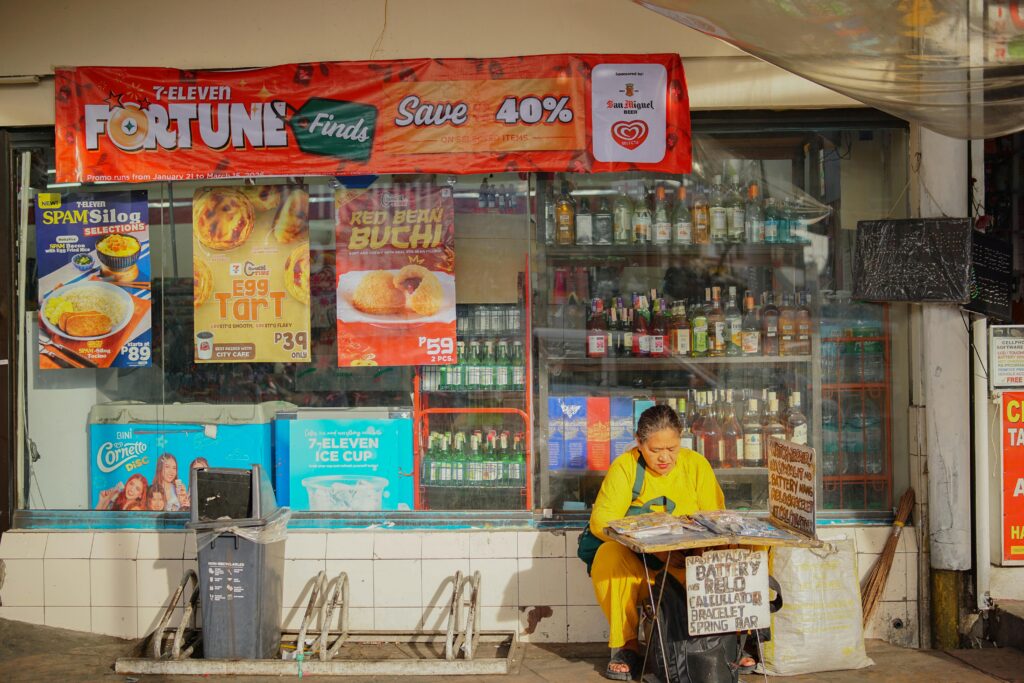
Here’s how to legally and profitably offer remittance services in your sari‑sari store.
Choose your remittance partner
You don’t need to build your own remittance system. Sari‑sari stores simply partner with established, BSP‑regulated providers. Each provider has its own strengths depending on your community’s needs.
| Provider | Brand Name | Best For… |
|---|---|---|
| Maya Business | Maya Center (Smart Padala) | Most familiar to locals; strong domestic remittance network |
| GCash | GCash Pera Outlet | Communities heavily using GCash for daily payments |
| Cebuana Lhuillier | Cebuana Quikz | Bank‑to‑bank or Cebuana‑to‑Cebuana transfers |
| GrowSari | GrowSari Digital | All‑in‑one app for load, bills, and remittance |
A sari‑sari store uses Maya Center for remittance, GCash Pera Outlet for cash‑in/cash‑out, and GrowSari for load—creating a full financial service hub.
Prepare the legal requirements
Because remittance involves money movement, the BSP requires strict compliance with KYC (Know Your Customer) and AMLA (Anti‑Money Laundering Act). Providers will ask for documents to ensure you are a legitimate business.
What you need
- Valid ID: PhilID, Passport, or Driver’s License
- DTI Registration: For sole proprietors
- Mayor’s/Barangay Business Permit: Proof that your store is legally operating
- BIR Certificate of Registration (Form 2303): Required for all digital merchants.
- Store Photo: A clear picture of your storefront with visible signage
Tip: Providers prefer stores with visible branding (e.g., “Smart Padala,” “GCash Pera Outlet”). It increases customer trust.
The application process
Most providers now use digital onboarding. You can apply using your smartphone and get approved within days.
Step‑by‑step process
- Download the merchant app: Maya Business App, GCash for Business, or GrowSari
- Submit your documents: Upload ID, permits, and store photo
- Complete AMLA training: Watch a short compliance video and pass a quiz
- Wait for approval: Usually 24–72 hours
- Receive your kit: Merchant QR, posters, and digital wallet access
Example: A store in Iloilo applied for Maya Center on a Monday and started processing remittances by Thursday.
How you earn (the profit model)
Remittance services are profitable because you earn from both commissions and convenience fees—without needing physical inventory.
Two income streams
- Provider Commission: ₱1–₱5 per transaction
- Convenience Fee: ₱10–₱30 per transaction (set by the store)
Sample computation
If you process 10 remittances per day at ₱20 convenience fee:
- Daily Income: ₱200
- Monthly Income: ₱6,000
- Provider Commission: Additional ₱300–₱500/month
Total Monthly Profit: ₱6,300–₱6,500
And this is pure service income—no spoilage, no inventory cost, no storage.
Safety and compliance rules
Because you are handling money, compliance protects both your store and your customers.
Verify IDs
Under BSP Circular 1170, you must verify the identity of anyone sending or receiving money. Use:
- PhilID (National ID)
- Driver’s License
- eGov PH App for digital verification
Maintain a logbook
Even if the app records transactions, keep a manual logbook with:
- Name of sender/receiver
- Reference number
- Date and time
Never record PINs or sensitive information.
Manage liquidity
You need both:
- Digital float: Money in your merchant wallet
- Physical cash: For cash‑out transactions
Example: If you have ₱50,000 in your digital wallet but only ₱1,000 in your drawer, you cannot process cash‑outs.
Remittance hacks
| Feature | Tip for Store Owners |
|---|---|
| Signage | Place “Smart Padala” or “GCash” banners at eye level to attract walk‑ins |
| Security | Install CCTV aimed at the remittance window to prevent disputes |
| Bundling | Upsell: “Gusto niyo po bang isabay ang Meralco or Water bill?” |
Conclusion
Offering remittance services is one of the most powerful ways to upgrade your sari‑sari store. It increases foot traffic, builds customer loyalty, and creates a steady stream of service income with minimal overhead. With BSP’s push for a cash‑lite economy, small stores are becoming essential financial access points for millions of Filipinos.
Choose the right partner, complete the legal requirements, follow compliance rules, and promote your service well. With the right setup, your sari‑sari store can become the go‑to financial